Saturday, September 14, 2013

What is Bad Faith Adjusting? Is my Insurance Company/Contractor Actingin Bad Faith?

Bad faith adjusting will end your career...


When you are adjusting in bad faith you are intentionally setting the claim up to be fixed (cleaned up) by another adjuster later on down the road.  In other words, you are being lazy!  Bad faith refers to breach of contract when dealing with all involved parties (including contractors) who will assume you are acting in good faith and fair dealing.  Acting in bad faith will end your career and can also put you in jail!

Bad faith involves being dishonest or fraudulent in a claim.  Examples of bad faith claim handling could be:

  • Entering into an agreement without any intent of living up to the terms that have been agreed upon. (not fulfilling the contractual obligations to the insured based on what is written in their insurance policy)

  • Knowingly misrepresenting the quality of an item you are attempting to settle with the insured.

  • Intent to deceive or mislead in order to gain some sort of advantage.

  • Failure to thoroughly investigate a claim.

  • Failure to promptly investigate the insured's property.

    • Time periods that are deemed acceptable in reference to the above item will be defined in the insurance policy.

  • Unreasonably delaying or denying payment.

  • Refusing to settle the claim in its entirety. (intentionally providing a "less than fair/reasonable" settlement on an item)

Bad faith is also a two way street.  Insureds (policy holders) and contractors may also be found guilty of acting in bad faith.  It usually involves falsifying information in an attempt to mislead the insurance company.  Yes, this includes eating deductibles!


Wednesday, September 11, 2013

Sept. 11th 2001 - Hurricane Erin (the hurricane that nobody remembers)

Today is a day of mourning and remembrance for many across the country.  But most have forgotten that there was a hurricane 200 miles east of New York the day that the terrorist attacks took place!  Meteorologists cant even recall this hurricane; because the horrific events of September 11th overshadowed our memories of anything else that happened in the world that day.  If this storm were 200 miles closer to NYC, then flights would have been cancelled and the World Trace Center would not have been attacked...  In the below picture you will find a satellite image of Hurricane Erin on Sept. 11th 2001.  If you look closely, you can see the dust over New York City from the twin towers...

May God continue to bless America!  Never forget to pray for your country, our troops and for your future generations to come!  Let us never forget the tragic events that took place of 9/11/2001...

Friday, August 30, 2013

List of Major Independent Adjusting Firms Now Hiring!

So you wanna' become an adjuster but you don't know who to work for or where to start. There are many independent adjusting firms/vendors out there who are always hiring! Some are big, others are small.  Hurricane season has had a late start this year, so many independent firms are still looking for bodies to fill the adjuster role. Hurricanes bring everyone with varying backgrounds out of the woodwork to adjust claims.   This can be a great opportunity for a new adjuster to get a foot in the door!  There aren't many requirements to become an insurance adjuster.  You just need to have a lot of common sense, a good work ethic and be willing to travel!

The first thing you'll need to do is become listed on an adjusting firm's roster.  To do this, you will most likely need to pass a brief exam (much like an online employment process for many retail stores).  You will also need to become certified and licensed to adjust.  Your independent firm will usually offer certification classes for you.  You may also need to pass a drug test (the independent adjusting firm will usually pay for this).  You also need to decide which firm you want to work for.  Depending on where you want to work can play a big role in this.  If you want to adjust part-time or locally only.  Then you may want to consider working for a smaller adjusting firm.  Smaller adjusting firms may be more flexible for you if you don't want to travel out of state to work.  Keep in mind, if you decide to work for a smaller firm, it doesn't guarantee you a "work from home" position.  You should always look at adjusting as a traveling profession; regardless of who you work for.  To find a local independent adjusting firm, utilize a search engine!  There are lots out there!  For a large list of independent firms/vendors you can visit the IA Employers Now Hiring page!

If you decide to work for one of the bigger adjusting firms, (these are the firms that adjust for the bigger insurance carriers and typically produce higher deployment opportunities) then here is a list of "the big four".

Worley Catastrophe Response

Eberl Claims Service

Pilot Catastrophe Services, INC.

E.A. Renfroe Catastrophe Claims Services

The most important thing for you to do is act!  If you are serious about entering this industry then you need to commit yourself to getting on a roster and receiving the necessary certifications/licenses so you can become eligible for deployment ASAP!  Educate yourself before you make your decision!  The biggest rookie mistake you can make is jumping in head first while biting off more than you can chew!  I see it happen all of the time to new adjusters!  There is a lot of opportunity and money to be made with this job!  But you need to understand everything that goes into this lifestyle before you commit yourself and quit your day job...  This is life changing income that can potentially change you and your family's life!  I have been very blessed and I want to pay it forward!  So please utilize this website to help you gain an understanding of what it takes to be a successful insurance claims professional!

Monday, August 19, 2013

Guaranteed SECRET way to get the Insurance Adjuster to pay for anything!

There isn't!  Everything is handled on a claim by claim basis.  It is based on an insurance adjuster's discretion and insurance carrier policy.  No two claims are alike.  So whenever you hear a contractor complain "You guys paid for this on another claim".  That's why...  Contracting and insurance adjusting are both very inconsistent industries.  Keep this in mind if you are creating estimates to send to the insurance companies for supplement approval.  The best way to get everything you are asking for is to ALWAYS act professional, kind, courteous and be fair.  The same can be said for the insurance adjuster.

I know many contractors who will ask for a full roof replacement, non-existing drip edge/gutter apron, the homeowner's air conditioner with the dog house roof and overhead & profit (O&P) all marked up to $45,000.00 for a 20 square, 3-tab roof.  These same contractors will act like stubborn 2 year olds when they don't get their way.  If you are going to ask for everything under the sun, then you need to act like a professional/reasonable person.

Sunday, August 18, 2013

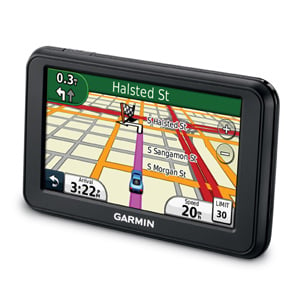
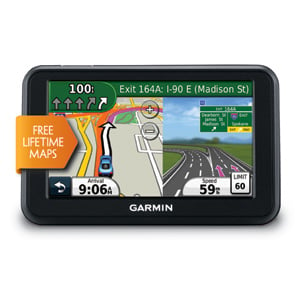
Garmin nüvi 40LM 4.3-Inch Portable GPS Navigator with Lifetime Maps (US)

Every adjuster will need a good navigation system!  Insurance adjusters will be traveling to very rural and sometimes isolated areas.  It is important to have a navigation system that is up to date and can give the adjuster the fastest route possible.  This is a priceless tool if your job requires you to constantly travel!  I've had my Garmin GPS for years now!  I update the map system on it before every storm deployment and I rarely get lost.  The user interface on the nüvi 40LM is easy to read and easy to use.  My wife uses a Tom Tom GPS; personally I can't stand the Tom Tom's user interface.  The Tom Tom feels cluttered, hard on the eyes and is difficult for me to use while on the road...  Take a look at the product details below to see if a Garmin GPS is for you!

Product Description


Edition: 4.3-Inch with Lifetime Maps


nüvi 40LM delivers you safely wherever life takes you. Designed to make

navigation easy, simply enter an address and premium features including lane assist with junction view, help you make all the right turns!

Start out for your destination and leave the navigating to nüvi 40LM. This device features a 4.3” (10.92 cm) touchscreen and provides accurate, turn-by-turn directions that speak street names. It also includes FREE lifetime map updates.

Get Turn-by-Turn Directions


nüvi 40LM's intuitive interface greets you with two simple choices: "Where To?" and "View Map." Touch the screen to easily look up addresses and services and to be guided to your destination with voice-prompted, turn-by-turn directions that speak street names. It comes preloaded with maps for


the lower 49 States. nüvi 40LM’s speed limit indicator shows you how fast you can go on most major roads. With its "Where Am I?" emergency locator, you always know your location. It also comes preloaded with more than 8 million points of interest (POIs) and offers the ability to add your own.

Enjoy FREE Lifetime Map Updates


With FREE lifetime map¹ updates, you always have the most up-to-date maps, POIs and navigation information available at your fingertips. Map updates are available for download up to 4 times a year with no subscription or update fees and no expiration dates.

Know the Lane Before It’s Too Late


Now there’s no more guessing which lane you need to be in to make an upcoming turn. Available in select metropolitan areas, lane assist with junction view guides you to the correct lane for an approaching turn or exit, making unfamiliar intersections and exits easy to navigate. It realistically displays road signs and junctions on your route along with arrows that indicate the proper lane for navigation.


What's in the Box


  • nüvi 40LM
  • City Navigator® NT data with preloaded street maps for the U.S.
  • Lifetime maps¹ (indicated by "LM" after model number on the box)
  • Vehicle suction cup mount²
  • Vehicle power cable
  • USB cable

  • Quick start manual

Product Information


Edition: 4.3-Inch with Lifetime Maps

Technical Details

  • Item Weight
5.3 ounces

  • Product Dimensions

0.7 x 4.9 x 3.1 inches
  • Item model number

010-00990-21
  • Batteries:

1 Nonstandard Battery batteries required. (included)
  • Display Size

4.3 inches
  • Warranty

Limited 1-year parts and labor
  • Battery Life

2 hours

Additional Information

  • ASIN

B0057ODG6Y

  • Customer Reviews

4.3 out of 5 stars See all reviews


4.3 out of 5 stars

  • Best Sellers Rank
#25 in Electronics (See top 100)
  • Shipping Weight
1 pounds (View shipping rates and policies)
  • Shipping

Currently, item can be shipped only within the U.S.
  • Date First Available

August 24, 2011

 View Customer Reviews for this product

Wednesday, August 14, 2013

How to earn quick and easy CE Credits online

So your adjuster state licensing is getting ready to expire and you haven't gotten nearly enough of the required continuing education credits...  Fear not!  There is no need to worry about the $50 per credit hour penalty!  You can easily acquire them in one night if you have a few hours to spare!  In this article I'm going to briefly go over how to quickly and easily earn CE credits by utilizing WebCE online!

All you have to do is go to www.webce.com.  From here click the Course Catalog link.  Then select your resident state from the diagram.  A list of license types will pop-up, choose "Adjuster". If no adjuster option is available then choose "Property & Casualty" (Adjuster and P&C are essentially the same thing anyway).  The following page will show you exactly how many credit hours you will need to fulfill your insurance license obligations.  You can also view your state's specific requirements in the Compliance Requirements section.
WebCE offers discount pricing when you bundle and purchase your CE courses at once.  You can expect to spend roughly $40 - $60 depending on how many credit hours your resident state requires.  Once you are in compliance with your resident state, most of the other states that you hold an adjuster license in will also deem you in compliance.  So the good news is "You don't have to repeat this process for every state you hold an adjuster license in!"  WebCE will also report your earned credits to your state for you.

You will be required to pass an exam once you have reviewed the CE course material.  If your resident state requires an exam proctor then you will need an adjuster buddy to login using their licensing credentials to verify that you did not cheat on the exam... Its a pain, but this is still the quickest, easiest and least expensive way to earn your CE credits!

Saturday, July 6, 2013

Step & Apron Flashings

Insurance companies are typically only going to pay for what is physically damaged to your property.  When the field adjuster comes out to visit you, don't be offended if an initial insurance estimate is given to you to perform repairs to your roof; instead of replacement of your roof.  Sometimes it can make more sense to attempt a repair (if logical).  If that repair will not work then the estimate may be revised at a later date (if warranted).  What most people don't understand, is that the field adjuster's estimate is not written in stone.  Revisions may be made at a later date to reconcile any concerns or disagreements that a contractor and/or homeowner may have.

One of the most common disagreements from the contractors, I've found, while adjusting is in regard to step flashings, chimney flashings and apron flashings.  These are not considered separate trades.  All roof flashings are considered roofing trades, as roofing sub crews will perform this work.  Therefore general contractor overhead and profit (O&P) is not warranted for roof & flashing replacements only.  Usually these items are not damaged during the storm.  However, these items will incur damage upon roof replacement.  Flashings are nailed down to the shingles and are sometimes sealed down with adhesive to prevent water from entering the home.  Each insurance carrier is going to approach flashing differently.  Most of them will not pay for these items up-front unless there if visible damage.  However, if the flashings are sealed down to the shingles with yucky puck, caulking or any other type of adhesive, the adjuster can usually justify replacement of these items as it can be easily photographed and shown to the insurance carrier that the flashing will incur damage.  Field adjusters are usually not going to pay for flashings up-front.  If you have concerns, call your insurance carrier and an inside adjuster (or call center adjuster) may be able to assist you.

Keep in mind that most insurance policies have a building code endorsement attached to the main insurance policy.  What this allows the adjuster to do, is allow extra funding within the insurance estimate to bring the damaged portions of the dwelling up to current building code specifications.  In most states, damaged or rusted flashings is a building code violation.  Please be sure to check with local building code enforcement to verify before filing supplement requests.  It would behoove you to find this written documentation and give it to your field adjuster during the inspection.