
Showing posts with label claims. Show all posts
Showing posts with label claims. Show all posts
Friday, May 22, 2015
Independent adjusters are seeing fewer deployments...
Yep... It's sad, but true! Some of the larger insurance companies, such as State Farm, are in the middle of a complete overhaul of operations. One of the reasons, is because independent adjusters are just too damn expensive!
An independent adjuster can make a whole lot of money on a typical 3 month long deployment. I was bringing in $15,000.00 a month back when I was at it. Mind you, this is before all of my own expenses; but that is a ton of cash to be giving a single adjuster for a deployment! Insurance carriers know this, and that is why they are switching over to hiring more staff adjusters than independent adjusters. They can keep their staff adjusters on a cushy salary all year long, and deploy them when needed. The typical staff adjuster salary ranges from $32,000.00 to $75,000.00 per year (the higher salaries usually belonging to the senior adjusters or trainers).
If you think about the economics and business behind all of that, it is way cheaper to have a staff adjuster on your payroll than to constantly be deploying independent adjusters....
Don't let that discourage you though! Just because some of the big dogs are restructuring their employees, work flow and office environment doesn't mean that the smaller insurance carriers are not deploying independents! If you haven't already stopped by, please check out the Independent Firms page to see an extensive list of independent adjusting firms that are always looking to add people to their rosters.
Smaller independent firms might be a great starting point for you. The smaller companies usually have more of a personal touch. You aren't just another number in line waiting to be called into the office for a job opportunity. If you can manage to score a great opportunity on a smaller adjusting firm roster; then you may very well see frequent deployment opportunities. Especially if your manager will write you a good review!
Use these small, but frequent deployment opportunities, that a smaller independent firm can provide, to build your resumé. A strong resumé with lots of practical deployment experience could lead to a potential staff adjusting job later on down the road. Don't let the job application for a staff position scare you! Lots of independent adjusters I know (who are looking to become staff adjusters) do not have a college degree, but got the job anyway. Most insurance carriers will state that a college degree is a requirement for application. In actuality, it is just a perk that they are looking for! APPLY ANYWAY! Take it from me! Insurance carriers are looking to hire based on experience. If you are a good fit, it won't matter what your educational background is! Put yourself out there! Whats the worst that could happen? Who cares if a few companies turn you down... That is all part of a typical job hunt! I turned down several job opportunities that didn't fit me; and I got turned away by several insurance carriers before I found a carrier that offered me a good job opportunity.
You won't know until you try!

Thursday, May 14, 2015
Eberl Blog
There are alot of resources out there to inform yourself about what the weather is doing in the United States. Eberl is one of the largest independent adjusting firms in the country; and they just so happen to have a blog that provides weather updates. This is beneficial to an adjuster, because if you read carefully enough, you can figure out when mass deployments may go out.
During big storms, such as hurricane Sandy, IA firms will often pre-deploy adjusters in preparation of immediate catastrophe work. Pay attention when companies like this make big postings! Make sure your contact information is up to date, you are listed as active on their roster, and all of your state adjusting licenses are current (and updated with your IA firm's records)!
You may find Eberl's blog here: http://www.eberls.com/blog/
If you are not on Eberls roster, it might be a good idea to apply while you are there. They work for the largest insurance company in the United States, State Farm. Which means more claims and more opportunities!
Tuesday, October 1, 2013
Eating a deductible is breaking the law! Do you need help finding a reputable contractor?
While some of us have been busy filling our down time from a deployment by playing Grand Theft Auto V online, watching the Breaking Bad Finale or being irritated by all of the media surrounding the Government Shutdown... Lets focus on a ethical hot topic that will have many contractors screaming in protest! Ignoring deductibles! This is a serious issue that could land the homeowner and contractor in jail and with some hefty DOI fines! (Department of Insurance) As an adjuster, it is important to be aware of this moral dilemma; because roughly 85% of all contractors are going to do this! (that's almost 9 out of 10 contractors)
By law, insureds are required to fiscally participate in a loss with the insurance company. This is why there are deductibles; and this is why everyone is required to pay a deductible to the insurance company whenever a loss is suffered.
"Eating a deductible" means that a contractor will attempt to negotiate with your insurance company so you do not have to pay your deductible on your claim. Your contractor may make this sound like a good deal; but the problem with this is that "eating a deductible" is classified as insurance fraud. In order for a contractor to do this, they would need to either: screw you over when you try to claim your RCBs (recoverable depreciation) or double invoice your insurance company. Double invoicing means that they will give the insured (you) an invoice for "xxx" dollar amount, while submitting a different invoice to the insurance company for a higher dollar amount. This higher dollar amount will conveniently be in the amount of your specific deductible. In other terms, your contractor is purposely lying to the insurance company! Once you (the insured/homeowner) have been made aware that your contractor is doing this, then you can be held liable as well!
This is the current Indiana insurance law which will hold true and be consistent with most states. Visit your local government facility to obtain the exact insurance law in your area.
INDIANA CODE 35-43-5-4.5
A person who knowingly and with intent to defraud:
(1) makes, utters, presents or causes to be presented to an insurer or insurance claimant, a claim statement that contains, false, incomplete, or misleading information concerning the claim.
(2) presents, causes to be presented, or prepares with knowledge or belief that it will be presented to or by an insurer, an oral, a written, or an electronic statement that the person knows to contain materially false information.
There ya' have it.... That is insurance fraud! Not a whole lot of room for grey area is there? If you and/or your contractor are found guilty of this, then you will have performed a Class C Felony! Once you commit a felony, you can no longer vote or purchase/carry a firearm. You will also face jail time and hefty penalties.
Now the question is... "Is my contractor doing this?" Unfortunately the answer is most likely, "Yes!" Most contractors are unaware that eating a deductible is insurance fraud; therefore most are going to openly advertise that they will do the job so you don't have to pay for your deductible... The competition is fierce out there! Especially after a new storm hits! Almost all contracting companies are going to feel inclined to offer "eating a deductible" to you because otherwise they don't feel like they can compete in the market. They can be a little sneaky with how they present this to you. They may also try to pressure you! You may have heard this before:
There are other problems that can also arise from "eating deductibles." Unless you live in a state that is RCV only (i.e. West Virginia) your insurance company is only going to give you a portion of your settlement up front. This is called Actual Cash Value or ACV. Without going into huge details, ACV payments are best described as "ransom money!" The insurance company doesn't want to overpay for your claim so they want to make sure you are going to actually do the work for the amount that has been settled/agreed upon. Your insurance company is going to ask for a contract or invoice from your contractor. They basically want to make sure you are legally contracted to complete the work before they release the rest of your settlement to you. If the insurance company receives an invoice from your contractor that is "xxx" less than the total claim settlement amount (assuming your contractor is not double invoicing and submits the invoice amount that he/she is actually charging you), then the insurance company is only going to pay you the costs you have incurred, less your deductible. In other words, you are getting a crappier roof than you deserve because you will still end up paying for your deductible!
I can guarantee you if your contractor is willing to cheat your insurance company, then they are going to cheat you too! It may come in the form of your deductible, but your contractor is going to "cut corners" elsewhere so they can still make some sort of profit on your job. You will get a lesser quality roof if you go with a contractor who is doing the job for your deductible!
"IF YOU ARE A CONTRACTOR WHO IS KNOWINGLY DOING THIS TO YOUR CUSTOMERS..... SHAME ON YOU!"
By law, insureds are required to fiscally participate in a loss with the insurance company. This is why there are deductibles; and this is why everyone is required to pay a deductible to the insurance company whenever a loss is suffered.
"Eating a deductible" means that a contractor will attempt to negotiate with your insurance company so you do not have to pay your deductible on your claim. Your contractor may make this sound like a good deal; but the problem with this is that "eating a deductible" is classified as insurance fraud. In order for a contractor to do this, they would need to either: screw you over when you try to claim your RCBs (recoverable depreciation) or double invoice your insurance company. Double invoicing means that they will give the insured (you) an invoice for "xxx" dollar amount, while submitting a different invoice to the insurance company for a higher dollar amount. This higher dollar amount will conveniently be in the amount of your specific deductible. In other terms, your contractor is purposely lying to the insurance company! Once you (the insured/homeowner) have been made aware that your contractor is doing this, then you can be held liable as well!
Lets take a look at how most state laws will define insurance fraud.
This is the current Indiana insurance law which will hold true and be consistent with most states. Visit your local government facility to obtain the exact insurance law in your area.
INDIANA CODE 35-43-5-4.5
A person who knowingly and with intent to defraud:
(1) makes, utters, presents or causes to be presented to an insurer or insurance claimant, a claim statement that contains, false, incomplete, or misleading information concerning the claim.
(2) presents, causes to be presented, or prepares with knowledge or belief that it will be presented to or by an insurer, an oral, a written, or an electronic statement that the person knows to contain materially false information.
There ya' have it.... That is insurance fraud! Not a whole lot of room for grey area is there? If you and/or your contractor are found guilty of this, then you will have performed a Class C Felony! Once you commit a felony, you can no longer vote or purchase/carry a firearm. You will also face jail time and hefty penalties.
Now the question is... "Is my contractor doing this?" Unfortunately the answer is most likely, "Yes!" Most contractors are unaware that eating a deductible is insurance fraud; therefore most are going to openly advertise that they will do the job so you don't have to pay for your deductible... The competition is fierce out there! Especially after a new storm hits! Almost all contracting companies are going to feel inclined to offer "eating a deductible" to you because otherwise they don't feel like they can compete in the market. They can be a little sneaky with how they present this to you. They may also try to pressure you! You may have heard this before:
- I'll just do the job for "xxx" amount less than what the insurance company pays you. That way you don't have to worry about paying for your deductible.
- I'll give you "xxx" amount off of your total job cost as an advertisement discount; but only if you let me put my sign in your yard!
- I don't need "xxx" amount that the insurance company paid you to do your job... I'm a lot cheaper than the competition. If you decide to use me today I can do your job for less and you can keep the extra money!
There are other problems that can also arise from "eating deductibles." Unless you live in a state that is RCV only (i.e. West Virginia) your insurance company is only going to give you a portion of your settlement up front. This is called Actual Cash Value or ACV. Without going into huge details, ACV payments are best described as "ransom money!" The insurance company doesn't want to overpay for your claim so they want to make sure you are going to actually do the work for the amount that has been settled/agreed upon. Your insurance company is going to ask for a contract or invoice from your contractor. They basically want to make sure you are legally contracted to complete the work before they release the rest of your settlement to you. If the insurance company receives an invoice from your contractor that is "xxx" less than the total claim settlement amount (assuming your contractor is not double invoicing and submits the invoice amount that he/she is actually charging you), then the insurance company is only going to pay you the costs you have incurred, less your deductible. In other words, you are getting a crappier roof than you deserve because you will still end up paying for your deductible!
I can guarantee you if your contractor is willing to cheat your insurance company, then they are going to cheat you too! It may come in the form of your deductible, but your contractor is going to "cut corners" elsewhere so they can still make some sort of profit on your job. You will get a lesser quality roof if you go with a contractor who is doing the job for your deductible!
"IF YOU ARE A CONTRACTOR WHO IS KNOWINGLY DOING THIS TO YOUR CUSTOMERS..... SHAME ON YOU!"
Friday, August 30, 2013
List of Major Independent Adjusting Firms Now Hiring!
So you wanna' become an adjuster but you don't know who to work for or where to start. There are many independent adjusting firms/vendors out there who are always hiring! Some are big, others are small. Hurricane season has had a late start this year, so many independent firms are still looking for bodies to fill the adjuster role. Hurricanes bring everyone with varying backgrounds out of the woodwork to adjust claims. This can be a great opportunity for a new adjuster to get a foot in the door! There aren't many requirements to become an insurance adjuster. You just need to have a lot of common sense, a good work ethic and be willing to travel!
The first thing you'll need to do is become listed on an adjusting firm's roster. To do this, you will most likely need to pass a brief exam (much like an online employment process for many retail stores). You will also need to become certified and licensed to adjust. Your independent firm will usually offer certification classes for you. You may also need to pass a drug test (the independent adjusting firm will usually pay for this). You also need to decide which firm you want to work for. Depending on where you want to work can play a big role in this. If you want to adjust part-time or locally only. Then you may want to consider working for a smaller adjusting firm. Smaller adjusting firms may be more flexible for you if you don't want to travel out of state to work. Keep in mind, if you decide to work for a smaller firm, it doesn't guarantee you a "work from home" position. You should always look at adjusting as a traveling profession; regardless of who you work for. To find a local independent adjusting firm, utilize a search engine! There are lots out there! For a large list of independent firms/vendors you can visit the IA Employers Now Hiring page!
If you decide to work for one of the bigger adjusting firms, (these are the firms that adjust for the bigger insurance carriers and typically produce higher deployment opportunities) then here is a list of "the big four".
Worley Catastrophe Response
Eberl Claims Service
Pilot Catastrophe Services, INC.
E.A. Renfroe Catastrophe Claims Services
The most important thing for you to do is act! If you are serious about entering this industry then you need to commit yourself to getting on a roster and receiving the necessary certifications/licenses so you can become eligible for deployment ASAP! Educate yourself before you make your decision! The biggest rookie mistake you can make is jumping in head first while biting off more than you can chew! I see it happen all of the time to new adjusters! There is a lot of opportunity and money to be made with this job! But you need to understand everything that goes into this lifestyle before you commit yourself and quit your day job... This is life changing income that can potentially change you and your family's life! I have been very blessed and I want to pay it forward! So please utilize this website to help you gain an understanding of what it takes to be a successful insurance claims professional!
Sunday, August 18, 2013
Garmin nüvi 40LM 4.3-Inch Portable GPS Navigator with Lifetime Maps (US)
Every adjuster will need a good navigation system! Insurance adjusters will be traveling to very rural and sometimes isolated areas. It is important to have a navigation system that is up to date and can give the adjuster the fastest route possible. This is a priceless tool if your job requires you to constantly travel! I've had my Garmin GPS for years now! I update the map system on it before every storm deployment and I rarely get lost. The user interface on the nüvi 40LM is easy to read and easy to use. My wife uses a Tom Tom GPS; personally I can't stand the Tom Tom's user interface. The Tom Tom feels cluttered, hard on the eyes and is difficult for me to use while on the road... Take a look at the product details below to see if a Garmin GPS is for you!
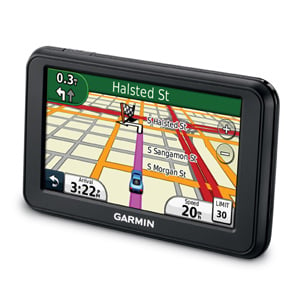
nüvi 40LM delivers you safely wherever life takes you. Designed to make
navigation easy, simply enter an address and premium features including lane assist with junction view, help you make all the right turns!
Start out for your destination and leave the navigating to nüvi 40LM. This device features a 4.3” (10.92 cm) touchscreen and provides accurate, turn-by-turn directions that speak street names. It also includes FREE lifetime map updates.
nüvi 40LM's intuitive interface greets you with two simple choices: "Where To?" and "View Map." Touch the screen to easily look up addresses and services and to be guided to your destination with voice-prompted, turn-by-turn directions that speak street names. It comes preloaded with maps for
the lower 49 States. nüvi 40LM’s speed limit indicator shows you how fast you can go on most major roads. With its "Where Am I?" emergency locator, you always know your location. It also comes preloaded with more than 8 million points of interest (POIs) and offers the ability to add your own.
With FREE lifetime map¹ updates, you always have the most up-to-date maps, POIs and navigation information available at your fingertips. Map updates are available for download up to 4 times a year with no subscription or update fees and no expiration dates.
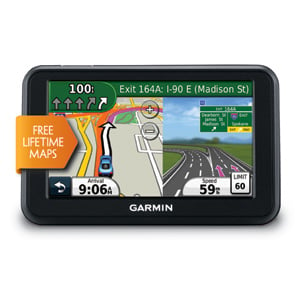
Now there’s no more guessing which lane you need to be in to make an upcoming turn. Available in select metropolitan areas, lane assist with junction view guides you to the correct lane for an approaching turn or exit, making unfamiliar intersections and exits easy to navigate. It realistically displays road signs and junctions on your route along with arrows that indicate the proper lane for navigation.
What's in the Box
Product Description
Edition: 4.3-Inch with Lifetime Maps
nüvi 40LM delivers you safely wherever life takes you. Designed to make
navigation easy, simply enter an address and premium features including lane assist with junction view, help you make all the right turns!
Start out for your destination and leave the navigating to nüvi 40LM. This device features a 4.3” (10.92 cm) touchscreen and provides accurate, turn-by-turn directions that speak street names. It also includes FREE lifetime map updates.
Get Turn-by-Turn Directions
nüvi 40LM's intuitive interface greets you with two simple choices: "Where To?" and "View Map." Touch the screen to easily look up addresses and services and to be guided to your destination with voice-prompted, turn-by-turn directions that speak street names. It comes preloaded with maps for
the lower 49 States. nüvi 40LM’s speed limit indicator shows you how fast you can go on most major roads. With its "Where Am I?" emergency locator, you always know your location. It also comes preloaded with more than 8 million points of interest (POIs) and offers the ability to add your own.
Enjoy FREE Lifetime Map Updates
With FREE lifetime map¹ updates, you always have the most up-to-date maps, POIs and navigation information available at your fingertips. Map updates are available for download up to 4 times a year with no subscription or update fees and no expiration dates.
Know the Lane Before It’s Too Late
Now there’s no more guessing which lane you need to be in to make an upcoming turn. Available in select metropolitan areas, lane assist with junction view guides you to the correct lane for an approaching turn or exit, making unfamiliar intersections and exits easy to navigate. It realistically displays road signs and junctions on your route along with arrows that indicate the proper lane for navigation.
What's in the Box
- nüvi 40LM
- City Navigator® NT data with preloaded street maps for the U.S.
- Lifetime maps¹ (indicated by "LM" after model number on the box)
- Vehicle suction cup mount²
- Vehicle power cable
- USB cable
Quick start manual
Product Information
Edition: 4.3-Inch with Lifetime Maps
Technical Details
| 5.3 ounces |
| 0.7 x 4.9 x 3.1 inches |
| 010-00990-21 |
| 1 Nonstandard Battery batteries required. (included) |
| 4.3 inches |
| Limited 1-year parts and labor |
| 2 hours |
Additional Information
| B0057ODG6Y |
| |
| #25 in Electronics (See top 100) |
| 1 pounds (View shipping rates and policies) |
| Currently, item can be shipped only within the U.S. |
| August 24, 2011 |
View Customer Reviews for this product
Friday, April 5, 2013
Local Woman Interviewed about Intense Hail Storm - Kapooyah!
This has been floating around the interwebs for awhile, and it still cracks me up every single time I watch it! A local woman is interviewed about a significant hail event that hit her neighborhood. Watch to see her hilarious explanation of the events that occurred!
Thursday, March 14, 2013
To O&P or not to O&P...
That is the question...
O&P stands for overhead and profit and is usually included into an insurance claim when a job warrants extra work/coordination of sub crews from a general contractor. It is extra money allowance of 10% overhead and 10% profit added to the overall claim settlement amount (20% total). The definition of overhead and profit inclusion is "Complexity of repairs or coordination of multiple trades". There is a lot of controversy surrounding what warrants O&P into an insurance claim. Arguments can easily be made on both sides of the fence. But it all comes down to how well the insurance adjuster can justify O&P inclusion into his or her file notes.
Once upon a time, insurance companies used to automatically include O&P into a job when 3 or more different trades were present in the claim. For example, if the roof was being replaced along with: an elevation of siding and interior drywall/paint repairs, then this job would quality for O&P for multiple trades (because there would be a total of 4 different trades in this example). This type of job is also complex (as some of the trades are contingent upon each other), which is also another reason why O&P would be warranted. However, it only takes a few bad eggs to spoil the batch for everyone... What insurance companies were finding is that some general contractors would purposely hire additional sub crews to perform miniscule/unnecessary tasks (such as hiring an HVAC tech solely to unhook the furnace cap during a roof replacement) or hiring a window installer to replace an exterior window screen, just so they could bill the insurance company for O&P. It is for this reason, that most insurance companies will look for "complexity of repairs" as another area to consider O&P.
So how could an adjuster justify coordination of multiple trades properly in his or her file notes? You could take the approach of:
"Overhead and profit is warranted on this job due to coordination of multiple trades and complexity of repairs. This job has complexity due to the need to coordinate between the roofing, siding, drywall and painting subcontractors and the homeowner. The painter cannot begin his work until the drywall subcontractor has finished his work and the mud is dry. The drywall subcontractor cannot begin his work until the roofing subcontractor is finished with his work and the roof stops leaking. All of this has to be coordinated with the homeowner’s schedule, as interior access will be necessary to complete the repairs; thus adding complexity to the job."
Feel free to paraphrase, but if you want to sound like a smarty pants and get management off of your back about your settlement decisions, then this example would be a good place to start in how you should structure your logic within a file note. Of course your photographs should also support justification of overhead and profit as well.
What should I do if I am not sure if a claim warrants overhead and profit?
You should review any settlement/coverage questions with your manager. But if your manager is not available and you are out in the field ready to make an on-site settlement then INCLUDE IT! If you are on the fence and there is any question in your mind at all about including O&P into a claim; then just include it!
You are more likely to get in trouble for not paying O&P when it should have been warranted, than vice-versa. There is an old saying that one of my old managers loved to throw around at the office "The tie goes to the runner!" It is just good customer service to include O&P as much as you can justify it. This will make the contractor happy, and in turn will make the homeowner happy; because that is just one less step that the homeowner will have to deal with. Homeowners HATE having to ask the insurance company for supplemental payments! The same cannot be said for the contractor ;)
Also think of it this way. If overhead and profit is included in the claim that you are adjusting, then you have a greater chance for the claim to reach eligibility for percentage file billing. Which is more money in your pocket! Everyone loves more money! It's a win-win situation! Just be sure you are not going crazy with it and that you can reasonably justify your thought process within your file notes. Un-ethical billing on your files can lead to a quick release from the storm and a probable DNR or (do not rehire) black-listed to your employment.
Friday, February 8, 2013
State of Emergency: NY, MA, CT, RI
Winter Storm Nemo is a monster! And it is only getting worse! (2/8/2013 - 2/9/2013)

The brunt end of the storm is currently in New Jersey and is headed toward Boston fast! A state of emergency has been issued for many areas of the northeastern US. Areas of New York, Massachusetts, Connecticut and Rhode Island have all issued travel bans. If you are in these areas and attempt to travel then you could be issued a hefty ticket. DO NOT TRAVEL IF YOU ARE IN THESE AREAS! Remember, you are not only putting your life at risk, but you will also be putting first responders at risk.
Winter Storm Nemo is intensifying and is projected to become worse later on tonight. Gusts in upwards of 50 mph are being reported. By 5 or 6am tomorrow (Feb. 9th) the storm will be ending for the western-most areas that have been affected. Hunker down, Bahston! It looks like you are going to be taking the brunt of this storm!
Stay safe and God bless! Click here to FIND more information on Winter Storm NEMO
Wednesday, January 2, 2013
Product Review of the Bosch DLR130K Digital Distance Measurer Kit
As an insurance claims adjuster, I am often asked "How do you adjust 5 or more claims per day, while producing quality inspections?" Besides general work experience, I will attribute part of my speed to the Bosch DLR130K Digital Distance laser measuring device. This niftly little device will save me up to 30 minutes or more, per interior inspection! Time is money to an insurance claims adjuster; and the Bosch DLR130K allows me to focus on more important elements of the damage assessment process. This was the first piece of equipment I purchased as an adjuster; and it was the best investment I have ever made! It also doubles as a fancy laser pointer to torture my dog and cat when I am at home. ;)
The Bosch DLR130K is easy to use. All you have to do is point and click, and the unit will display the distance (or how far away) an object is. It is accurate to within a sixteenth of an inch! This is very useful to me when I am measuring eave heights, fence lengths, elevations, cabinets, interior rooms and ceiling heights. The Bosch DLR130K Digital Distance Measurer can be displayed in inches/feet, decimals and metrics. It will also measure areas and volumes. The Bosch DLR130K is very durable. I use mine every day and it has been abused! I've dropped it countless times onto the concrete and even off of roof tops and it still works perfectly!
The Bosch DLR130K laser measurer is also very reasonably priced! The Bosch DLR130K Digital Distance Measurer is currently listed on Amazon.com for only $89.99 new. I would strongly recommend this item if you are an insurance claims adjuster, general contractor, carpenter or if you are just a handy person who enjoys fixer-uppers! For more insurance claims adjuster related items, please visit the Insurance Adjusting Equipment page and the "What equipment will I need when adjusting insurance claims?" page.
Tuesday, January 1, 2013
Insurance Claims Adjuster Jobs
Here is a current listing of insurance claims adjuster jobs (auto, health, liability, subrogation, worker's compensation and property) throughout the United States:
- Insurance Claims Adjuster / IACP Certified Auto Appraisers / Expert Witness (auto) - Houston, Texas
Auto PD / BI Insurance Claims Adjuster (auto) - Sacramento, California
- Health Insurance Claims Adjuster Needed (health) - Westlake, Ohio
- Insurance Claims Adjuster (property adjuster) - Pennsylvania and New Jersey
- Insurance Adjuster (property adjuster) - Fort Wayne, Indiana
- Insurance Claims Adjuster (liability and property) - Bloomfield, New Jersey
- Insurance Claims Adjuster (property) - Chicago, Illinois
Entry Level Auto Insurance Claims Adjuster Trainee (auto) - Addison, Texas
- Insurance Claims Adjuster - Richmond, Virginia
- Auto Insurance Claims Adjuster (auto) - Mesa, Arizona
Resident Material Damage Claims Adjuster (auto and property) - Lawton, Oklahoma
- Allstate - Total Loss Claims Adjuster (auto) - Roseville, California
- Geico - Auto Damage Adjuster Intern Job (auto) - Albany, New York
- Casualty Adjuster Trainee Job - Phoenix, Arizona
- Claims Adjuster - Lincoln, Nebraska
- Senior General Liability Adjuster Job - Seattle, Washington
- Senior Commercial Liability Adjuster - Chicago, Illinois
- Commercial General Liability Adjuster - Oakland, California
Workers' Compensation Claims Adjuster, Level I - Oklahoma City, Oklahoma
- Claims Adjuster Licensed - Dallas, Texas
- Claims Adjuster Trainee - Saint Louis, Missouri
- Geico - Field Auto Damage Adjuster / Appraiser - Trainee (auto) - San Jose, California
- Claims Adjuster - Charles City, Iowa
- Progressive - Claims Adjuster Trainee Job - Phoenix, Arizona
Field Claim Adjuster - Equipment Breakdown Claims - Los Angeles, California
- Subrogation Claims Adjuster - Lynnwood, Washington
- Claims Field Adjuster (property) - Denver, Colorado
- Claims Field Adjuster Job - Saint Louis, Missouri
Subscribe to:
Posts (Atom)