
Friday, May 22, 2015
Independent adjusters are seeing fewer deployments...
Yep... It's sad, but true! Some of the larger insurance companies, such as State Farm, are in the middle of a complete overhaul of operations. One of the reasons, is because independent adjusters are just too damn expensive!
An independent adjuster can make a whole lot of money on a typical 3 month long deployment. I was bringing in $15,000.00 a month back when I was at it. Mind you, this is before all of my own expenses; but that is a ton of cash to be giving a single adjuster for a deployment! Insurance carriers know this, and that is why they are switching over to hiring more staff adjusters than independent adjusters. They can keep their staff adjusters on a cushy salary all year long, and deploy them when needed. The typical staff adjuster salary ranges from $32,000.00 to $75,000.00 per year (the higher salaries usually belonging to the senior adjusters or trainers).
If you think about the economics and business behind all of that, it is way cheaper to have a staff adjuster on your payroll than to constantly be deploying independent adjusters....
Don't let that discourage you though! Just because some of the big dogs are restructuring their employees, work flow and office environment doesn't mean that the smaller insurance carriers are not deploying independents! If you haven't already stopped by, please check out the Independent Firms page to see an extensive list of independent adjusting firms that are always looking to add people to their rosters.
Smaller independent firms might be a great starting point for you. The smaller companies usually have more of a personal touch. You aren't just another number in line waiting to be called into the office for a job opportunity. If you can manage to score a great opportunity on a smaller adjusting firm roster; then you may very well see frequent deployment opportunities. Especially if your manager will write you a good review!
Use these small, but frequent deployment opportunities, that a smaller independent firm can provide, to build your resumé. A strong resumé with lots of practical deployment experience could lead to a potential staff adjusting job later on down the road. Don't let the job application for a staff position scare you! Lots of independent adjusters I know (who are looking to become staff adjusters) do not have a college degree, but got the job anyway. Most insurance carriers will state that a college degree is a requirement for application. In actuality, it is just a perk that they are looking for! APPLY ANYWAY! Take it from me! Insurance carriers are looking to hire based on experience. If you are a good fit, it won't matter what your educational background is! Put yourself out there! Whats the worst that could happen? Who cares if a few companies turn you down... That is all part of a typical job hunt! I turned down several job opportunities that didn't fit me; and I got turned away by several insurance carriers before I found a carrier that offered me a good job opportunity.
You won't know until you try!

Thursday, May 14, 2015
Eberl Blog
There are alot of resources out there to inform yourself about what the weather is doing in the United States. Eberl is one of the largest independent adjusting firms in the country; and they just so happen to have a blog that provides weather updates. This is beneficial to an adjuster, because if you read carefully enough, you can figure out when mass deployments may go out.
During big storms, such as hurricane Sandy, IA firms will often pre-deploy adjusters in preparation of immediate catastrophe work. Pay attention when companies like this make big postings! Make sure your contact information is up to date, you are listed as active on their roster, and all of your state adjusting licenses are current (and updated with your IA firm's records)!
You may find Eberl's blog here: http://www.eberls.com/blog/
If you are not on Eberls roster, it might be a good idea to apply while you are there. They work for the largest insurance company in the United States, State Farm. Which means more claims and more opportunities!
Wednesday, April 8, 2015
Hail is upon us
Storm season is here and hail is upon us! Just a friendly reminder to renew/apply for your state licenses now, as IA firms will likely be sending out deployments soon! Now would also be a great time to update your availability with your IA firm or to apply to be on the roster for a new IA firm. If you need to see a large list of IA firms, who are always looking to add new adjusters to their rosters, then please visit the IA Firms page. http://insurance-adjuster-help.blogspot.com/p/ia-employers-now-hiring.html

The more IA rosters you are available on, the higher the chances for a deployment (especially if you are new to the industry)
Saturday, March 28, 2015
Back Online!
Good news everyone!
I've finally managed to get the old blog up and running onto a new site! I know I said I was going to have this accomplished a long time ago, but.... well.... Life happened! I was blessed enough to welcome the birth of my first baby girl into this world. So that kept me busy for awhile!
For the most part, everything transferred over from the wordpress site. Some pictures did not transfer over, and the coding also got goofed up in some posts. I will be slowly correcting this information over time. So if you experience a few glitches in the matrix, I apologize! Feel free to visit the facebook or twitter site to notify me of any glitches you are finding so I can get em' all fixed up!
More to come, so stay tuned!
Thursday, October 3, 2013
Tropical Storm Karen - Evacuations in Louisiana
Even though she is only a tropical storm, the people of Louisiana are no strangers to flooding and hurricane-type weather! Grand Isle Mayor David Camardelle is not taking any chances and has called for voluntary evacuations. As of Thursday evening these are still voluntary. But if the storm intensifies the mayor may issue a mandatory evacuation.
New Orleans is not calling for any evacuations at this time, but is heavily monitoring the situation.
Tropical Storm Karen is headed towards the southeastern tip of Louisiana and the southern coasts of Mississippi and Alabama. The western tip of Florida may also be affected. Stay tuned to The Weather Channel for up-to-date coverage on the storm! Below you will find an image from The Weather Channel of Tropical Storm Karen's projected path.
Tuesday, October 1, 2013
Eating a deductible is breaking the law! Do you need help finding a reputable contractor?
While some of us have been busy filling our down time from a deployment by playing Grand Theft Auto V online, watching the Breaking Bad Finale or being irritated by all of the media surrounding the Government Shutdown... Lets focus on a ethical hot topic that will have many contractors screaming in protest! Ignoring deductibles! This is a serious issue that could land the homeowner and contractor in jail and with some hefty DOI fines! (Department of Insurance) As an adjuster, it is important to be aware of this moral dilemma; because roughly 85% of all contractors are going to do this! (that's almost 9 out of 10 contractors)
By law, insureds are required to fiscally participate in a loss with the insurance company. This is why there are deductibles; and this is why everyone is required to pay a deductible to the insurance company whenever a loss is suffered.
"Eating a deductible" means that a contractor will attempt to negotiate with your insurance company so you do not have to pay your deductible on your claim. Your contractor may make this sound like a good deal; but the problem with this is that "eating a deductible" is classified as insurance fraud. In order for a contractor to do this, they would need to either: screw you over when you try to claim your RCBs (recoverable depreciation) or double invoice your insurance company. Double invoicing means that they will give the insured (you) an invoice for "xxx" dollar amount, while submitting a different invoice to the insurance company for a higher dollar amount. This higher dollar amount will conveniently be in the amount of your specific deductible. In other terms, your contractor is purposely lying to the insurance company! Once you (the insured/homeowner) have been made aware that your contractor is doing this, then you can be held liable as well!
This is the current Indiana insurance law which will hold true and be consistent with most states. Visit your local government facility to obtain the exact insurance law in your area.
INDIANA CODE 35-43-5-4.5
A person who knowingly and with intent to defraud:
(1) makes, utters, presents or causes to be presented to an insurer or insurance claimant, a claim statement that contains, false, incomplete, or misleading information concerning the claim.
(2) presents, causes to be presented, or prepares with knowledge or belief that it will be presented to or by an insurer, an oral, a written, or an electronic statement that the person knows to contain materially false information.
There ya' have it.... That is insurance fraud! Not a whole lot of room for grey area is there? If you and/or your contractor are found guilty of this, then you will have performed a Class C Felony! Once you commit a felony, you can no longer vote or purchase/carry a firearm. You will also face jail time and hefty penalties.
Now the question is... "Is my contractor doing this?" Unfortunately the answer is most likely, "Yes!" Most contractors are unaware that eating a deductible is insurance fraud; therefore most are going to openly advertise that they will do the job so you don't have to pay for your deductible... The competition is fierce out there! Especially after a new storm hits! Almost all contracting companies are going to feel inclined to offer "eating a deductible" to you because otherwise they don't feel like they can compete in the market. They can be a little sneaky with how they present this to you. They may also try to pressure you! You may have heard this before:
There are other problems that can also arise from "eating deductibles." Unless you live in a state that is RCV only (i.e. West Virginia) your insurance company is only going to give you a portion of your settlement up front. This is called Actual Cash Value or ACV. Without going into huge details, ACV payments are best described as "ransom money!" The insurance company doesn't want to overpay for your claim so they want to make sure you are going to actually do the work for the amount that has been settled/agreed upon. Your insurance company is going to ask for a contract or invoice from your contractor. They basically want to make sure you are legally contracted to complete the work before they release the rest of your settlement to you. If the insurance company receives an invoice from your contractor that is "xxx" less than the total claim settlement amount (assuming your contractor is not double invoicing and submits the invoice amount that he/she is actually charging you), then the insurance company is only going to pay you the costs you have incurred, less your deductible. In other words, you are getting a crappier roof than you deserve because you will still end up paying for your deductible!
I can guarantee you if your contractor is willing to cheat your insurance company, then they are going to cheat you too! It may come in the form of your deductible, but your contractor is going to "cut corners" elsewhere so they can still make some sort of profit on your job. You will get a lesser quality roof if you go with a contractor who is doing the job for your deductible!
"IF YOU ARE A CONTRACTOR WHO IS KNOWINGLY DOING THIS TO YOUR CUSTOMERS..... SHAME ON YOU!"
By law, insureds are required to fiscally participate in a loss with the insurance company. This is why there are deductibles; and this is why everyone is required to pay a deductible to the insurance company whenever a loss is suffered.
"Eating a deductible" means that a contractor will attempt to negotiate with your insurance company so you do not have to pay your deductible on your claim. Your contractor may make this sound like a good deal; but the problem with this is that "eating a deductible" is classified as insurance fraud. In order for a contractor to do this, they would need to either: screw you over when you try to claim your RCBs (recoverable depreciation) or double invoice your insurance company. Double invoicing means that they will give the insured (you) an invoice for "xxx" dollar amount, while submitting a different invoice to the insurance company for a higher dollar amount. This higher dollar amount will conveniently be in the amount of your specific deductible. In other terms, your contractor is purposely lying to the insurance company! Once you (the insured/homeowner) have been made aware that your contractor is doing this, then you can be held liable as well!
Lets take a look at how most state laws will define insurance fraud.
This is the current Indiana insurance law which will hold true and be consistent with most states. Visit your local government facility to obtain the exact insurance law in your area.
INDIANA CODE 35-43-5-4.5
A person who knowingly and with intent to defraud:
(1) makes, utters, presents or causes to be presented to an insurer or insurance claimant, a claim statement that contains, false, incomplete, or misleading information concerning the claim.
(2) presents, causes to be presented, or prepares with knowledge or belief that it will be presented to or by an insurer, an oral, a written, or an electronic statement that the person knows to contain materially false information.
There ya' have it.... That is insurance fraud! Not a whole lot of room for grey area is there? If you and/or your contractor are found guilty of this, then you will have performed a Class C Felony! Once you commit a felony, you can no longer vote or purchase/carry a firearm. You will also face jail time and hefty penalties.
Now the question is... "Is my contractor doing this?" Unfortunately the answer is most likely, "Yes!" Most contractors are unaware that eating a deductible is insurance fraud; therefore most are going to openly advertise that they will do the job so you don't have to pay for your deductible... The competition is fierce out there! Especially after a new storm hits! Almost all contracting companies are going to feel inclined to offer "eating a deductible" to you because otherwise they don't feel like they can compete in the market. They can be a little sneaky with how they present this to you. They may also try to pressure you! You may have heard this before:
- I'll just do the job for "xxx" amount less than what the insurance company pays you. That way you don't have to worry about paying for your deductible.
- I'll give you "xxx" amount off of your total job cost as an advertisement discount; but only if you let me put my sign in your yard!
- I don't need "xxx" amount that the insurance company paid you to do your job... I'm a lot cheaper than the competition. If you decide to use me today I can do your job for less and you can keep the extra money!
There are other problems that can also arise from "eating deductibles." Unless you live in a state that is RCV only (i.e. West Virginia) your insurance company is only going to give you a portion of your settlement up front. This is called Actual Cash Value or ACV. Without going into huge details, ACV payments are best described as "ransom money!" The insurance company doesn't want to overpay for your claim so they want to make sure you are going to actually do the work for the amount that has been settled/agreed upon. Your insurance company is going to ask for a contract or invoice from your contractor. They basically want to make sure you are legally contracted to complete the work before they release the rest of your settlement to you. If the insurance company receives an invoice from your contractor that is "xxx" less than the total claim settlement amount (assuming your contractor is not double invoicing and submits the invoice amount that he/she is actually charging you), then the insurance company is only going to pay you the costs you have incurred, less your deductible. In other words, you are getting a crappier roof than you deserve because you will still end up paying for your deductible!
I can guarantee you if your contractor is willing to cheat your insurance company, then they are going to cheat you too! It may come in the form of your deductible, but your contractor is going to "cut corners" elsewhere so they can still make some sort of profit on your job. You will get a lesser quality roof if you go with a contractor who is doing the job for your deductible!
"IF YOU ARE A CONTRACTOR WHO IS KNOWINGLY DOING THIS TO YOUR CUSTOMERS..... SHAME ON YOU!"
Saturday, September 14, 2013
What is Bad Faith Adjusting? Is my Insurance Company/Contractor Actingin Bad Faith?
Bad faith adjusting will end your career...
When you are adjusting in bad faith you are intentionally setting the claim up to be fixed (cleaned up) by another adjuster later on down the road. In other words, you are being lazy! Bad faith refers to breach of contract when dealing with all involved parties (including contractors) who will assume you are acting in good faith and fair dealing. Acting in bad faith will end your career and can also put you in jail!
Bad faith involves being dishonest or fraudulent in a claim. Examples of bad faith claim handling could be:
- Entering into an agreement without any intent of living up to the terms that have been agreed upon. (not fulfilling the contractual obligations to the insured based on what is written in their insurance policy)
- Knowingly misrepresenting the quality of an item you are attempting to settle with the insured.
- Intent to deceive or mislead in order to gain some sort of advantage.
- Failure to thoroughly investigate a claim.
- Failure to promptly investigate the insured's property.
- Time periods that are deemed acceptable in reference to the above item will be defined in the insurance policy.
- Unreasonably delaying or denying payment.
- Refusing to settle the claim in its entirety. (intentionally providing a "less than fair/reasonable" settlement on an item)
Bad faith is also a two way street. Insureds (policy holders) and contractors may also be found guilty of acting in bad faith. It usually involves falsifying information in an attempt to mislead the insurance company. Yes, this includes eating deductibles!
Wednesday, September 11, 2013
Sept. 11th 2001 - Hurricane Erin (the hurricane that nobody remembers)
Today is a day of mourning and remembrance for many across the country. But most have forgotten that there was a hurricane 200 miles east of New York the day that the terrorist attacks took place! Meteorologists cant even recall this hurricane; because the horrific events of September 11th overshadowed our memories of anything else that happened in the world that day. If this storm were 200 miles closer to NYC, then flights would have been cancelled and the World Trace Center would not have been attacked... In the below picture you will find a satellite image of Hurricane Erin on Sept. 11th 2001. If you look closely, you can see the dust over New York City from the twin towers...
May God continue to bless America! Never forget to pray for your country, our troops and for your future generations to come! Let us never forget the tragic events that took place of 9/11/2001...
May God continue to bless America! Never forget to pray for your country, our troops and for your future generations to come! Let us never forget the tragic events that took place of 9/11/2001...
Friday, August 30, 2013
List of Major Independent Adjusting Firms Now Hiring!
So you wanna' become an adjuster but you don't know who to work for or where to start. There are many independent adjusting firms/vendors out there who are always hiring! Some are big, others are small. Hurricane season has had a late start this year, so many independent firms are still looking for bodies to fill the adjuster role. Hurricanes bring everyone with varying backgrounds out of the woodwork to adjust claims. This can be a great opportunity for a new adjuster to get a foot in the door! There aren't many requirements to become an insurance adjuster. You just need to have a lot of common sense, a good work ethic and be willing to travel!
The first thing you'll need to do is become listed on an adjusting firm's roster. To do this, you will most likely need to pass a brief exam (much like an online employment process for many retail stores). You will also need to become certified and licensed to adjust. Your independent firm will usually offer certification classes for you. You may also need to pass a drug test (the independent adjusting firm will usually pay for this). You also need to decide which firm you want to work for. Depending on where you want to work can play a big role in this. If you want to adjust part-time or locally only. Then you may want to consider working for a smaller adjusting firm. Smaller adjusting firms may be more flexible for you if you don't want to travel out of state to work. Keep in mind, if you decide to work for a smaller firm, it doesn't guarantee you a "work from home" position. You should always look at adjusting as a traveling profession; regardless of who you work for. To find a local independent adjusting firm, utilize a search engine! There are lots out there! For a large list of independent firms/vendors you can visit the IA Employers Now Hiring page!
If you decide to work for one of the bigger adjusting firms, (these are the firms that adjust for the bigger insurance carriers and typically produce higher deployment opportunities) then here is a list of "the big four".
Worley Catastrophe Response
Eberl Claims Service
Pilot Catastrophe Services, INC.
E.A. Renfroe Catastrophe Claims Services
The most important thing for you to do is act! If you are serious about entering this industry then you need to commit yourself to getting on a roster and receiving the necessary certifications/licenses so you can become eligible for deployment ASAP! Educate yourself before you make your decision! The biggest rookie mistake you can make is jumping in head first while biting off more than you can chew! I see it happen all of the time to new adjusters! There is a lot of opportunity and money to be made with this job! But you need to understand everything that goes into this lifestyle before you commit yourself and quit your day job... This is life changing income that can potentially change you and your family's life! I have been very blessed and I want to pay it forward! So please utilize this website to help you gain an understanding of what it takes to be a successful insurance claims professional!
Monday, August 19, 2013
Guaranteed SECRET way to get the Insurance Adjuster to pay for anything!
There isn't! Everything is handled on a claim by claim basis. It is based on an insurance adjuster's discretion and insurance carrier policy. No two claims are alike. So whenever you hear a contractor complain "You guys paid for this on another claim". That's why... Contracting and insurance adjusting are both very inconsistent industries. Keep this in mind if you are creating estimates to send to the insurance companies for supplement approval. The best way to get everything you are asking for is to ALWAYS act professional, kind, courteous and be fair. The same can be said for the insurance adjuster.
I know many contractors who will ask for a full roof replacement, non-existing drip edge/gutter apron, the homeowner's air conditioner with the dog house roof and overhead & profit (O&P) all marked up to $45,000.00 for a 20 square, 3-tab roof. These same contractors will act like stubborn 2 year olds when they don't get their way. If you are going to ask for everything under the sun, then you need to act like a professional/reasonable person.
I know many contractors who will ask for a full roof replacement, non-existing drip edge/gutter apron, the homeowner's air conditioner with the dog house roof and overhead & profit (O&P) all marked up to $45,000.00 for a 20 square, 3-tab roof. These same contractors will act like stubborn 2 year olds when they don't get their way. If you are going to ask for everything under the sun, then you need to act like a professional/reasonable person.
Sunday, August 18, 2013
Garmin nüvi 40LM 4.3-Inch Portable GPS Navigator with Lifetime Maps (US)
Every adjuster will need a good navigation system! Insurance adjusters will be traveling to very rural and sometimes isolated areas. It is important to have a navigation system that is up to date and can give the adjuster the fastest route possible. This is a priceless tool if your job requires you to constantly travel! I've had my Garmin GPS for years now! I update the map system on it before every storm deployment and I rarely get lost. The user interface on the nüvi 40LM is easy to read and easy to use. My wife uses a Tom Tom GPS; personally I can't stand the Tom Tom's user interface. The Tom Tom feels cluttered, hard on the eyes and is difficult for me to use while on the road... Take a look at the product details below to see if a Garmin GPS is for you!
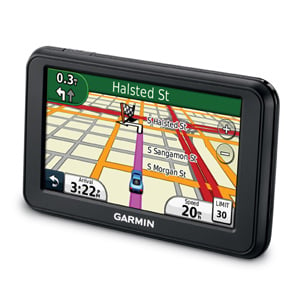
nüvi 40LM delivers you safely wherever life takes you. Designed to make
navigation easy, simply enter an address and premium features including lane assist with junction view, help you make all the right turns!
Start out for your destination and leave the navigating to nüvi 40LM. This device features a 4.3” (10.92 cm) touchscreen and provides accurate, turn-by-turn directions that speak street names. It also includes FREE lifetime map updates.
nüvi 40LM's intuitive interface greets you with two simple choices: "Where To?" and "View Map." Touch the screen to easily look up addresses and services and to be guided to your destination with voice-prompted, turn-by-turn directions that speak street names. It comes preloaded with maps for
the lower 49 States. nüvi 40LM’s speed limit indicator shows you how fast you can go on most major roads. With its "Where Am I?" emergency locator, you always know your location. It also comes preloaded with more than 8 million points of interest (POIs) and offers the ability to add your own.
With FREE lifetime map¹ updates, you always have the most up-to-date maps, POIs and navigation information available at your fingertips. Map updates are available for download up to 4 times a year with no subscription or update fees and no expiration dates.
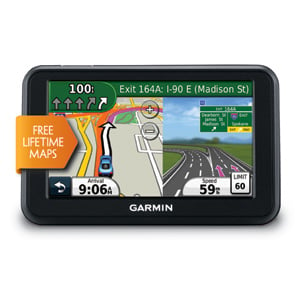
Now there’s no more guessing which lane you need to be in to make an upcoming turn. Available in select metropolitan areas, lane assist with junction view guides you to the correct lane for an approaching turn or exit, making unfamiliar intersections and exits easy to navigate. It realistically displays road signs and junctions on your route along with arrows that indicate the proper lane for navigation.
What's in the Box
Product Description
Edition: 4.3-Inch with Lifetime Maps
nüvi 40LM delivers you safely wherever life takes you. Designed to make
navigation easy, simply enter an address and premium features including lane assist with junction view, help you make all the right turns!
Start out for your destination and leave the navigating to nüvi 40LM. This device features a 4.3” (10.92 cm) touchscreen and provides accurate, turn-by-turn directions that speak street names. It also includes FREE lifetime map updates.
Get Turn-by-Turn Directions
nüvi 40LM's intuitive interface greets you with two simple choices: "Where To?" and "View Map." Touch the screen to easily look up addresses and services and to be guided to your destination with voice-prompted, turn-by-turn directions that speak street names. It comes preloaded with maps for
the lower 49 States. nüvi 40LM’s speed limit indicator shows you how fast you can go on most major roads. With its "Where Am I?" emergency locator, you always know your location. It also comes preloaded with more than 8 million points of interest (POIs) and offers the ability to add your own.
Enjoy FREE Lifetime Map Updates
With FREE lifetime map¹ updates, you always have the most up-to-date maps, POIs and navigation information available at your fingertips. Map updates are available for download up to 4 times a year with no subscription or update fees and no expiration dates.
Know the Lane Before It’s Too Late
Now there’s no more guessing which lane you need to be in to make an upcoming turn. Available in select metropolitan areas, lane assist with junction view guides you to the correct lane for an approaching turn or exit, making unfamiliar intersections and exits easy to navigate. It realistically displays road signs and junctions on your route along with arrows that indicate the proper lane for navigation.
What's in the Box
- nüvi 40LM
- City Navigator® NT data with preloaded street maps for the U.S.
- Lifetime maps¹ (indicated by "LM" after model number on the box)
- Vehicle suction cup mount²
- Vehicle power cable
- USB cable
Quick start manual
Product Information
Edition: 4.3-Inch with Lifetime Maps
Technical Details
| 5.3 ounces |
| 0.7 x 4.9 x 3.1 inches |
| 010-00990-21 |
| 1 Nonstandard Battery batteries required. (included) |
| 4.3 inches |
| Limited 1-year parts and labor |
| 2 hours |
Additional Information
| B0057ODG6Y |
| |
| #25 in Electronics (See top 100) |
| 1 pounds (View shipping rates and policies) |
| Currently, item can be shipped only within the U.S. |
| August 24, 2011 |
View Customer Reviews for this product
Wednesday, August 14, 2013
How to earn quick and easy CE Credits online
So your adjuster state licensing is getting ready to expire and you haven't gotten nearly enough of the required continuing education credits... Fear not! There is no need to worry about the $50 per credit hour penalty! You can easily acquire them in one night if you have a few hours to spare! In this article I'm going to briefly go over how to quickly and easily earn CE credits by utilizing WebCE online!
All you have to do is go to www.webce.com. From here click the Course Catalog link. Then select your resident state from the diagram. A list of license types will pop-up, choose "Adjuster". If no adjuster option is available then choose "Property & Casualty" (Adjuster and P&C are essentially the same thing anyway). The following page will show you exactly how many credit hours you will need to fulfill your insurance license obligations. You can also view your state's specific requirements in the Compliance Requirements section.
WebCE offers discount pricing when you bundle and purchase your CE courses at once. You can expect to spend roughly $40 - $60 depending on how many credit hours your resident state requires. Once you are in compliance with your resident state, most of the other states that you hold an adjuster license in will also deem you in compliance. So the good news is "You don't have to repeat this process for every state you hold an adjuster license in!" WebCE will also report your earned credits to your state for you.
You will be required to pass an exam once you have reviewed the CE course material. If your resident state requires an exam proctor then you will need an adjuster buddy to login using their licensing credentials to verify that you did not cheat on the exam... Its a pain, but this is still the quickest, easiest and least expensive way to earn your CE credits!
Saturday, July 6, 2013
Step & Apron Flashings
Insurance companies are typically only going to pay for what is physically damaged to your property. When the field adjuster comes out to visit you, don't be offended if an initial insurance estimate is given to you to perform repairs to your roof; instead of replacement of your roof. Sometimes it can make more sense to attempt a repair (if logical). If that repair will not work then the estimate may be revised at a later date (if warranted). What most people don't understand, is that the field adjuster's estimate is not written in stone. Revisions may be made at a later date to reconcile any concerns or disagreements that a contractor and/or homeowner may have.
One of the most common disagreements from the contractors, I've found, while adjusting is in regard to step flashings, chimney flashings and apron flashings. These are not considered separate trades. All roof flashings are considered roofing trades, as roofing sub crews will perform this work. Therefore general contractor overhead and profit (O&P) is not warranted for roof & flashing replacements only. Usually these items are not damaged during the storm. However, these items will incur damage upon roof replacement. Flashings are nailed down to the shingles and are sometimes sealed down with adhesive to prevent water from entering the home. Each insurance carrier is going to approach flashing differently. Most of them will not pay for these items up-front unless there if visible damage. However, if the flashings are sealed down to the shingles with yucky puck, caulking or any other type of adhesive, the adjuster can usually justify replacement of these items as it can be easily photographed and shown to the insurance carrier that the flashing will incur damage. Field adjusters are usually not going to pay for flashings up-front. If you have concerns, call your insurance carrier and an inside adjuster (or call center adjuster) may be able to assist you.
Keep in mind that most insurance policies have a building code endorsement attached to the main insurance policy. What this allows the adjuster to do, is allow extra funding within the insurance estimate to bring the damaged portions of the dwelling up to current building code specifications. In most states, damaged or rusted flashings is a building code violation. Please be sure to check with local building code enforcement to verify before filing supplement requests. It would behoove you to find this written documentation and give it to your field adjuster during the inspection.
Tuesday, May 28, 2013
Helpful Supplies for Hurricane Claims
With hurricane season roughly 3 days away it is important to keep your bags packed and to call your dispatcher ASAP; so your adjusting firm has your current availability status. If you do get called out, be prepared to sleep in your vehicle for a few days! I spent 5 days in my truck for Super-storm Sandy... Lots of homeowners and utility companies will be occupying every single hotel room you can find, so bring some blankets and other necessary supplies to prepare for the possibility of being "homeless" for a few days/weeks.
Also, this thing is pretty neat too! I would be jealous if I saw you on a storm-site with this...
They also make a version of this tent for SUV's. Full sized air mattresses for truck beds are available too!
- Baby wipes: If you are not going to have a hotel room for awhile, bring some baby-wipes so you can take a bum shower at the gas station. While it may not sound very glorious, it'll make you feel a little bit more comfortable.
- Bring extra gas: If there is a gas shortage, you may find yourself in the weeds. Bring a few extra gallons of gas with you before you head out!
- Buy a lock for your supplies! There were a lot of adjusters involved in Sandy who had their trucks broken into and other supplies stolen. Gas shortage was so bad that adjuster vehicles were having their gas tanks siphoned! Buy a bike-lock to secure your belongings and a tarp to hide everything as best as you can!
Also, this thing is pretty neat too! I would be jealous if I saw you on a storm-site with this...
They also make a version of this tent for SUV's. Full sized air mattresses for truck beds are available too!
Monday, May 13, 2013
How to set yourself apart from other adjusters

So its a few weeks into your storm deployment. You are all caught up on your contacts. You are scheduled out at-least 3 weeks. You've settled and closed a few dozen claims. Now what? It feels good to finally catch your breath and relax, right? While it is healthy to give yourself a breather; now couldn't be a more important/crucial point for your deployment!
Some of you may start to feel like you are over that hill and that things are easing up. While this may be true, the one thing you need to remember is to stay on your game! This is the point in the storm where you can greatly differentiate yourself from the other adjusters on-site. This could buy you more time deployed on storm if you handle everything right! By now you should be receiving return phone calls from homeowners you have already inspected. Make it a goal to respond to these people within 24 hours! Agents and homeowners often complain about their adjuster's lengthy response time for voice messages. They don't always understand how busy we are... Do your managers a favor and respond before these complaints reach them!
You may also be overhearing word of potential HOT claims in the office. These are usually homeowners that are upset because another adjuster may be 3 weeks or further out on their schedule. While it is impossible to make "everyone" happy, you could earn a few brownie points by making room in your schedule to take a HOT claim off of your manager's hands. However, don't reschedule someone just to make an impatient homeowner happy. You owe it to your homeowners to keep your word with your appointments. Make yourself known and tell your manager that you would be willing to take an extra claim or two to help out. Don't do this if you do not feel comfortable taking on extra work! If you are absolutely booked solid, its okay to turn down a few claims. Remember, you still need to keep a high standard of quality on all of your claim files. Don't do anything that would hinder your best performance!
I'm not telling you to be a pest while your in the office. After-all, nobody likes a brown nose... Approach everything from a genuine, realistic perspective. Don't be a stranger! Face time is one of the most important things you could do for your career! Make yourself known to your peers! You are just a name on a roster unless others can associate your face to that name. It is common sense for higher-ups to keep the claim handlers they know, and even more common sense to keep the claim handlers that are willing to go an extra mile to lend a helping hand!
Friday, April 19, 2013
How to make GREAT first contact phone calls
This is the hardest part of the storm for many new adjusters. There is a lot of pressure that comes with a new storm. A big part of this stress can be contributed to the pressure of making quality first contact phone calls with the policy holders (within a reasonable time-frame). It is not unusual for an adjuster to arrive on site and be dumped with 50 to 80 claims right out of the gate! All of these policy holders need to be contacted ASAP to make management happy and to adhere to good customer service practices.
It is crucially important to arrive on site and to get your storms off to a good start; because it will help build your confidence and set your mood for the rest of the storm! I have met many new guys who are too focused on performing inspections as soon as humanly possible. Unfortunately these adjusters never stick around because they will be back-logged with too many claims. Ive met too many adjusters who put themselves in a hole that they cannot get out of; because they didn't allow themselves the proper amount of time to schedule everyone. DON'T LET THIS HAPPEN TO YOU!!!
It is crucially important to arrive on site and to get your storms off to a good start; because it will help build your confidence and set your mood for the rest of the storm! I have met many new guys who are too focused on performing inspections as soon as humanly possible. Unfortunately these adjusters never stick around because they will be back-logged with too many claims. Ive met too many adjusters who put themselves in a hole that they cannot get out of; because they didn't allow themselves the proper amount of time to schedule everyone. DON'T LET THIS HAPPEN TO YOU!!!
How soon do I need to contact everyone?
- Depending on the insurance carrier, most companies will expect you to have everyone contacted within 24 - 48 hours of receiving the claim. It is possible to do! You just need to allow yourself enough time to focus on calling everyone before you attempt to perform any inspections.
How much time should I set aside after arriving on-site so I can get everyone called?
- A reasonable time-frame would be 2 or possibly 3 days (depending on your initial claim load). A good way to judge would be to allow yourself 1 day per every 25 claims you receive. If you give yourself this time when you start receiving claims, your going to earn a lot of respect from management! Managers usually have to hassle the other adjusters who do not take the time to call homeowners. You will look like a stud-muffin if you do this step!
What questions should I ask the policy holders?
- What damage did you sustain?
- This will help save you some detective work when you arrive at the home.
- This gives the homeowner a chance to address any specific concerns they may have.
- How old is your roof?
- The age of the roof plays a HUGE role in determining repairability!
- Is there any interior damage?
- Usually I encourage all of my homeowners to be present for the inspection. Sometimes it is not possible to work around their schedule and inspections will have to be performed without the homeowner being present. If there is interior damage, then there will need to be someone present so you can access and photograph the damage. If you ask this question and find out that there is no interior damage, then it becomes that much easier to set your schedule (because the homeowner doesn't necessarily need to be present).
- Do you have a contractor involved?
- Contractors are usually the first people to notify the homeowner that they have sustained storm damage. If the homeowner is comfortable with their contractor they will often times want their contractor to be present for your inspection. Always be sure to notify the homeowner that the contractor is welcome to be present for the inspection! This scares a lot of new guys because they don't want to argue. But it will save you a lot of back end work later on, because you won't have to be dealing with as many supplement requests later on during the storm. Get the contractor to meet with you and document if this particular contractor agrees with your inspection results (or not!).
Is your home 2 story and/or steep?
- This is probably the most important question to ask! Because if the roof is 2 story and/or steep and you are not comfortable climbing it, then it will need to be referred over to a 2 story & steep team (or another adjuster who is willing to climb big roofs). Not every insurance carrier utilizes a 2 story and steep team. If you end up with one of these insurance carriers, don't be afraid to ask a manager or another adjuster for help! It's much better to ask for help, instead of falling off of a roof and dying! It is important to remember that this does not give you permission to refer every roof that looks "mean" over to a 2 story team! The roof will need to be at-least 7/12 in pitch and/or 2 stories tall. If the roof has a single story access YOU CAN CLIMB IT! Unless you need a special 2 story ladder or need to perform a double pull to access the whole roof, do not refer a tall roof to the 2 story and steep team! (ITS VERY ANNOYING)
Verify their deductible and mortgage company!
- Sometimes a policy holder will be thrown back when they hear that their deductible has risen to $1,000.00 from $500.00. Ask them this question so they can get their insurance agent involved if they believe there is an error. The more detective work you do from the beginning the quicker the claim can be settled!
- Mortgage companies NEED TO BE VERIFIED! By law, if the Coverage A (building/dwelling) damages exceed $7,500.00, the mortgage company NEEDS to be included! Or if the mortgage company is considered a "dollar-one mortgagee" then you will need to include the mortgage company regardless! (even if you only write a check for 1 dollar!) If the incorrect mortgage company is written on the check, then the insured will not be able to deposit it into their account! This makes for a very angry homeowner!
*****IMPORTANT NOTE***** If you do not include a mortgagee that needs to be included on the check, then you may face some serious fines!
Wednesday, April 10, 2013
First Big CAT of the Season! Indiana gets CREAMED by Hail!
Alright, it's that time! All you adjusters out there START DOING YOUR HAPPY HAIL DANCE! I know I have been! ***see below video of happy, chubby kid dancing (that about sums up my dance moves!)***
The Midwest got CREAMED by hail today! Areas of Indianapolis got hit with 1" to 2" sized, hard hail stones that have busted out numerous car windows and hit an unsuspecting panhandler in the face! OUCH! Currently Missouri has had a tornado cause some damage and forecasters are saying that it's going to get dangerous tonight (because people will be sleeping when round 2 hits). Keep safe if you are in the splash zone! And get your bags packed if your an adjuster who is licensed in Indiana and/or Missouri! Heads up Memphis! You're next!
[caption id="attachment_557" align="alignleft" width="200"] A local beggar was hit in the face by a hail stone today[/caption]
[caption id="attachment_558" align="alignright" width="265"] 4/10/2013[/caption]

The Midwest got CREAMED by hail today! Areas of Indianapolis got hit with 1" to 2" sized, hard hail stones that have busted out numerous car windows and hit an unsuspecting panhandler in the face! OUCH! Currently Missouri has had a tornado cause some damage and forecasters are saying that it's going to get dangerous tonight (because people will be sleeping when round 2 hits). Keep safe if you are in the splash zone! And get your bags packed if your an adjuster who is licensed in Indiana and/or Missouri! Heads up Memphis! You're next!
[caption id="attachment_557" align="alignleft" width="200"]
 A local beggar was hit in the face by a hail stone today[/caption]
[caption id="attachment_558" align="alignright" width="265"]
 4/10/2013[/caption]

Friday, April 5, 2013
Local Woman Interviewed about Intense Hail Storm - Kapooyah!
This has been floating around the interwebs for awhile, and it still cracks me up every single time I watch it! A local woman is interviewed about a significant hail event that hit her neighborhood. Watch to see her hilarious explanation of the events that occurred!
Thursday, March 14, 2013
To O&P or not to O&P...
That is the question...
O&P stands for overhead and profit and is usually included into an insurance claim when a job warrants extra work/coordination of sub crews from a general contractor. It is extra money allowance of 10% overhead and 10% profit added to the overall claim settlement amount (20% total). The definition of overhead and profit inclusion is "Complexity of repairs or coordination of multiple trades". There is a lot of controversy surrounding what warrants O&P into an insurance claim. Arguments can easily be made on both sides of the fence. But it all comes down to how well the insurance adjuster can justify O&P inclusion into his or her file notes.
Once upon a time, insurance companies used to automatically include O&P into a job when 3 or more different trades were present in the claim. For example, if the roof was being replaced along with: an elevation of siding and interior drywall/paint repairs, then this job would quality for O&P for multiple trades (because there would be a total of 4 different trades in this example). This type of job is also complex (as some of the trades are contingent upon each other), which is also another reason why O&P would be warranted. However, it only takes a few bad eggs to spoil the batch for everyone... What insurance companies were finding is that some general contractors would purposely hire additional sub crews to perform miniscule/unnecessary tasks (such as hiring an HVAC tech solely to unhook the furnace cap during a roof replacement) or hiring a window installer to replace an exterior window screen, just so they could bill the insurance company for O&P. It is for this reason, that most insurance companies will look for "complexity of repairs" as another area to consider O&P.
So how could an adjuster justify coordination of multiple trades properly in his or her file notes? You could take the approach of:
"Overhead and profit is warranted on this job due to coordination of multiple trades and complexity of repairs. This job has complexity due to the need to coordinate between the roofing, siding, drywall and painting subcontractors and the homeowner. The painter cannot begin his work until the drywall subcontractor has finished his work and the mud is dry. The drywall subcontractor cannot begin his work until the roofing subcontractor is finished with his work and the roof stops leaking. All of this has to be coordinated with the homeowner’s schedule, as interior access will be necessary to complete the repairs; thus adding complexity to the job."
Feel free to paraphrase, but if you want to sound like a smarty pants and get management off of your back about your settlement decisions, then this example would be a good place to start in how you should structure your logic within a file note. Of course your photographs should also support justification of overhead and profit as well.
What should I do if I am not sure if a claim warrants overhead and profit?
You should review any settlement/coverage questions with your manager. But if your manager is not available and you are out in the field ready to make an on-site settlement then INCLUDE IT! If you are on the fence and there is any question in your mind at all about including O&P into a claim; then just include it!
You are more likely to get in trouble for not paying O&P when it should have been warranted, than vice-versa. There is an old saying that one of my old managers loved to throw around at the office "The tie goes to the runner!" It is just good customer service to include O&P as much as you can justify it. This will make the contractor happy, and in turn will make the homeowner happy; because that is just one less step that the homeowner will have to deal with. Homeowners HATE having to ask the insurance company for supplemental payments! The same cannot be said for the contractor ;)
Also think of it this way. If overhead and profit is included in the claim that you are adjusting, then you have a greater chance for the claim to reach eligibility for percentage file billing. Which is more money in your pocket! Everyone loves more money! It's a win-win situation! Just be sure you are not going crazy with it and that you can reasonably justify your thought process within your file notes. Un-ethical billing on your files can lead to a quick release from the storm and a probable DNR or (do not rehire) black-listed to your employment.
Monday, March 4, 2013
Johnson Level & Tool 750 Pitch and Slope Locator - Product Review
Finding the pitch of a roof is easy! Especially for those of us who have enough roof inspections under our belt to use our ankles as an impromptu pitch gage. However, even the most experienced adjuster will need to carry a pitch gauge with them at all times; because most insurance companies and independent vendors require their adjusters to photograph the pitch of a roof (for billing purposes). Others who have not had the luxury of growing up around general construction practices may have a difficult time determining a roof's pitch (especially if you don't know the math behind it).
The Johnson Level & Tool 750 Pitch and Slope Locator makes finding the pitch of a roof extremely simple! All you have to do is place the bottom of the pitch gauge on the roof, and it will display the roof's pitch for you!
The Johnson Level & Tool 750 Pitch and Slope Locator features a high impact plastic body and a crystal clear acrylic lens with easy to read graduations. Personally, despite what the video above says, I have had an extremely hard time finding anything related to a roofing pitch locator at all of the local hardware stores. Neither Lowes, Home Depot, Sears, Menards, Northern Tool and Equipment nor Sam's Club carry a pitch/slope locator in their stores. The only place I have had any consistent luck finding one of these is on Amazon.com
 . Currently there is nowhere else that sells this item for such a low/reasonable price! It would behoove you to take advantage of this blog post and buy one right now before they run out of stock! This can be a very difficult item to locate and is essential to your adjuster arsenal!
For a list of adjuster equipment that only the "big boys" will use, visit the Insurance Adjuster Equipment page.
Subscribe to:
Posts (Atom)